
Software Development & IT Services – Buyers pay for the business model, not the sector
Digital Services M&A Report Q3 2026
Q3 2026 – M&A trends, valuation multiples and transactions
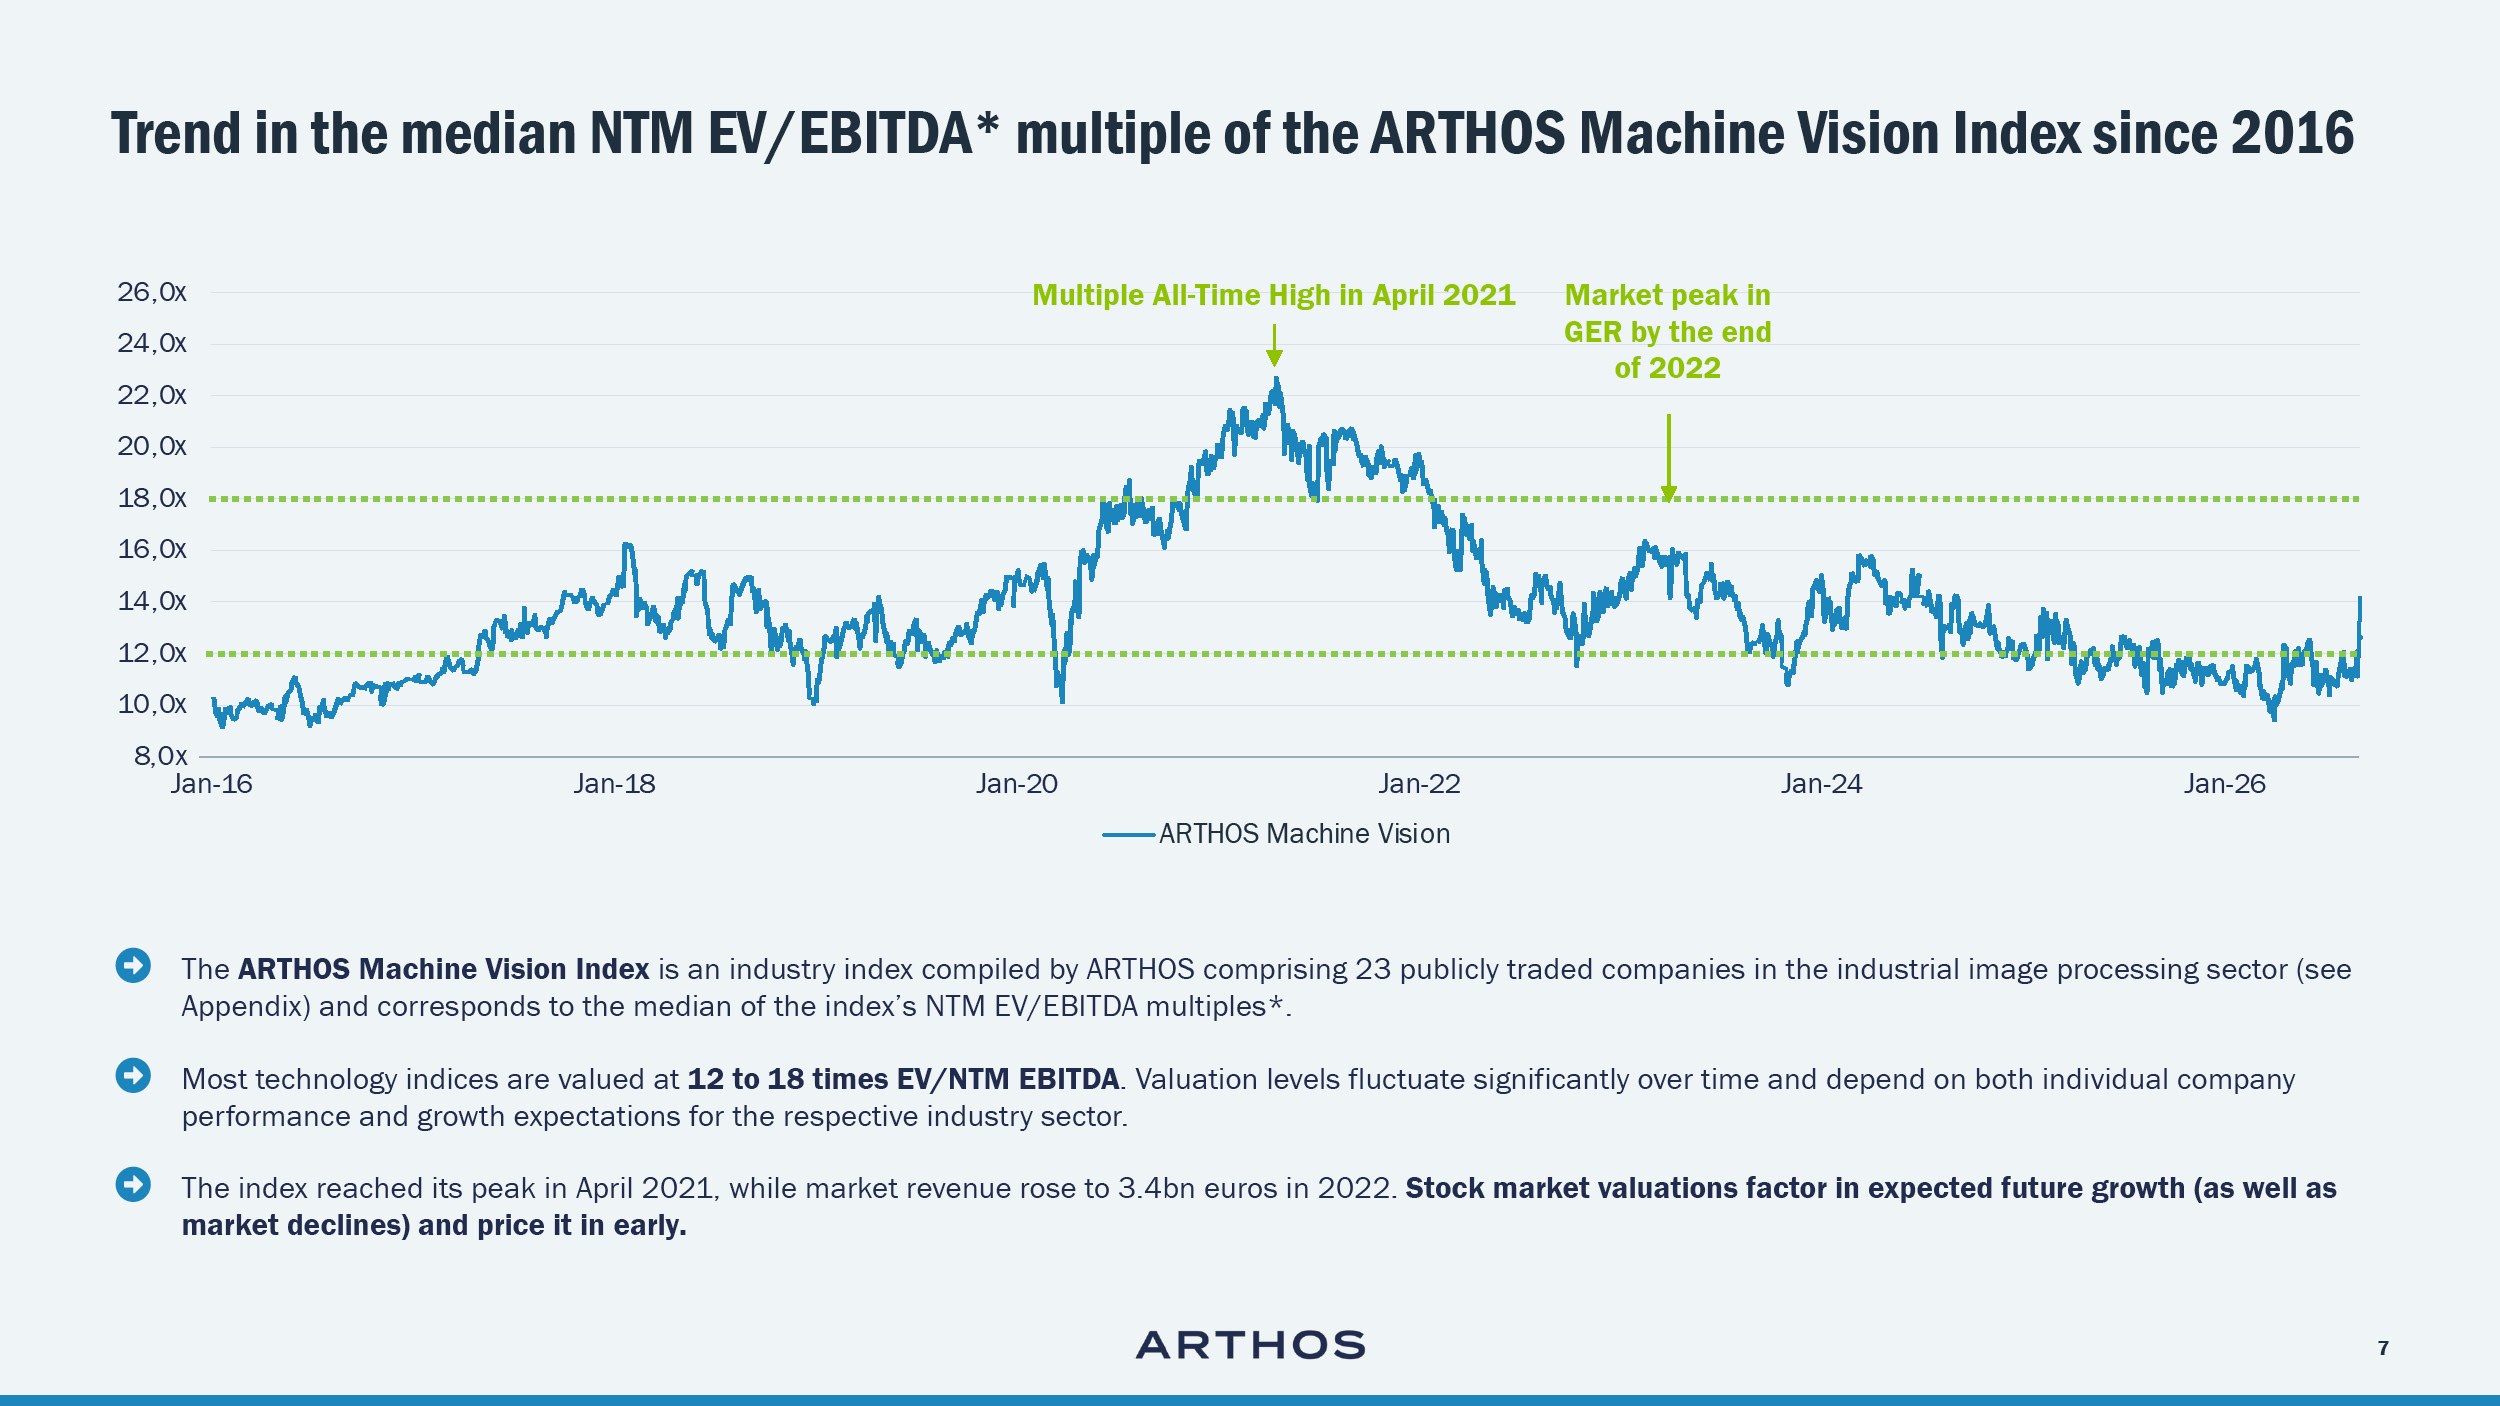
AI-related Vision stocks skyrocketed in H1 2026, but since August have fallen and settled at reasonable levels. Remarkably, valuations of traditional Machine Vision companies have improved significantly since spring.
We see the following three primary trends:
Managing Partner ARTHOS
Experte für Sensors, Automation, Semiconductor & Photonics
Due to their large share of exports, sales volumes of German Machine Vision (MV) companies are an excellent indicator of the global Machine Vision market. The stock market already anticipated the market decline from 2023 to 2025 in spring 2022 (see pages 8 and 9). Since April 2026, we have seen a recovery in Machine Vision stock valuations, driven by expectations of future growth. This trend was not affected by the market correction in AI-related vision stocks that took place since August – the outlook for Machine Vision is really good!
As outlined on pages 13 ff., we noted an all-time high in transactions announced in Q2 2026. In Q3, we saw announcements of larger transactions, including Cognex’s acquisition of RealSense for $500mn, SiMa.ai’s and RobCo’s capital raises making them unicorns, and the public takeover of Varex Imaging by Teledyne for c. $1.1bn in cash. This strong M&A demand for vision companies reflects continued interest in businesses targeting attractive future growth markets, particularly AI and robotics.
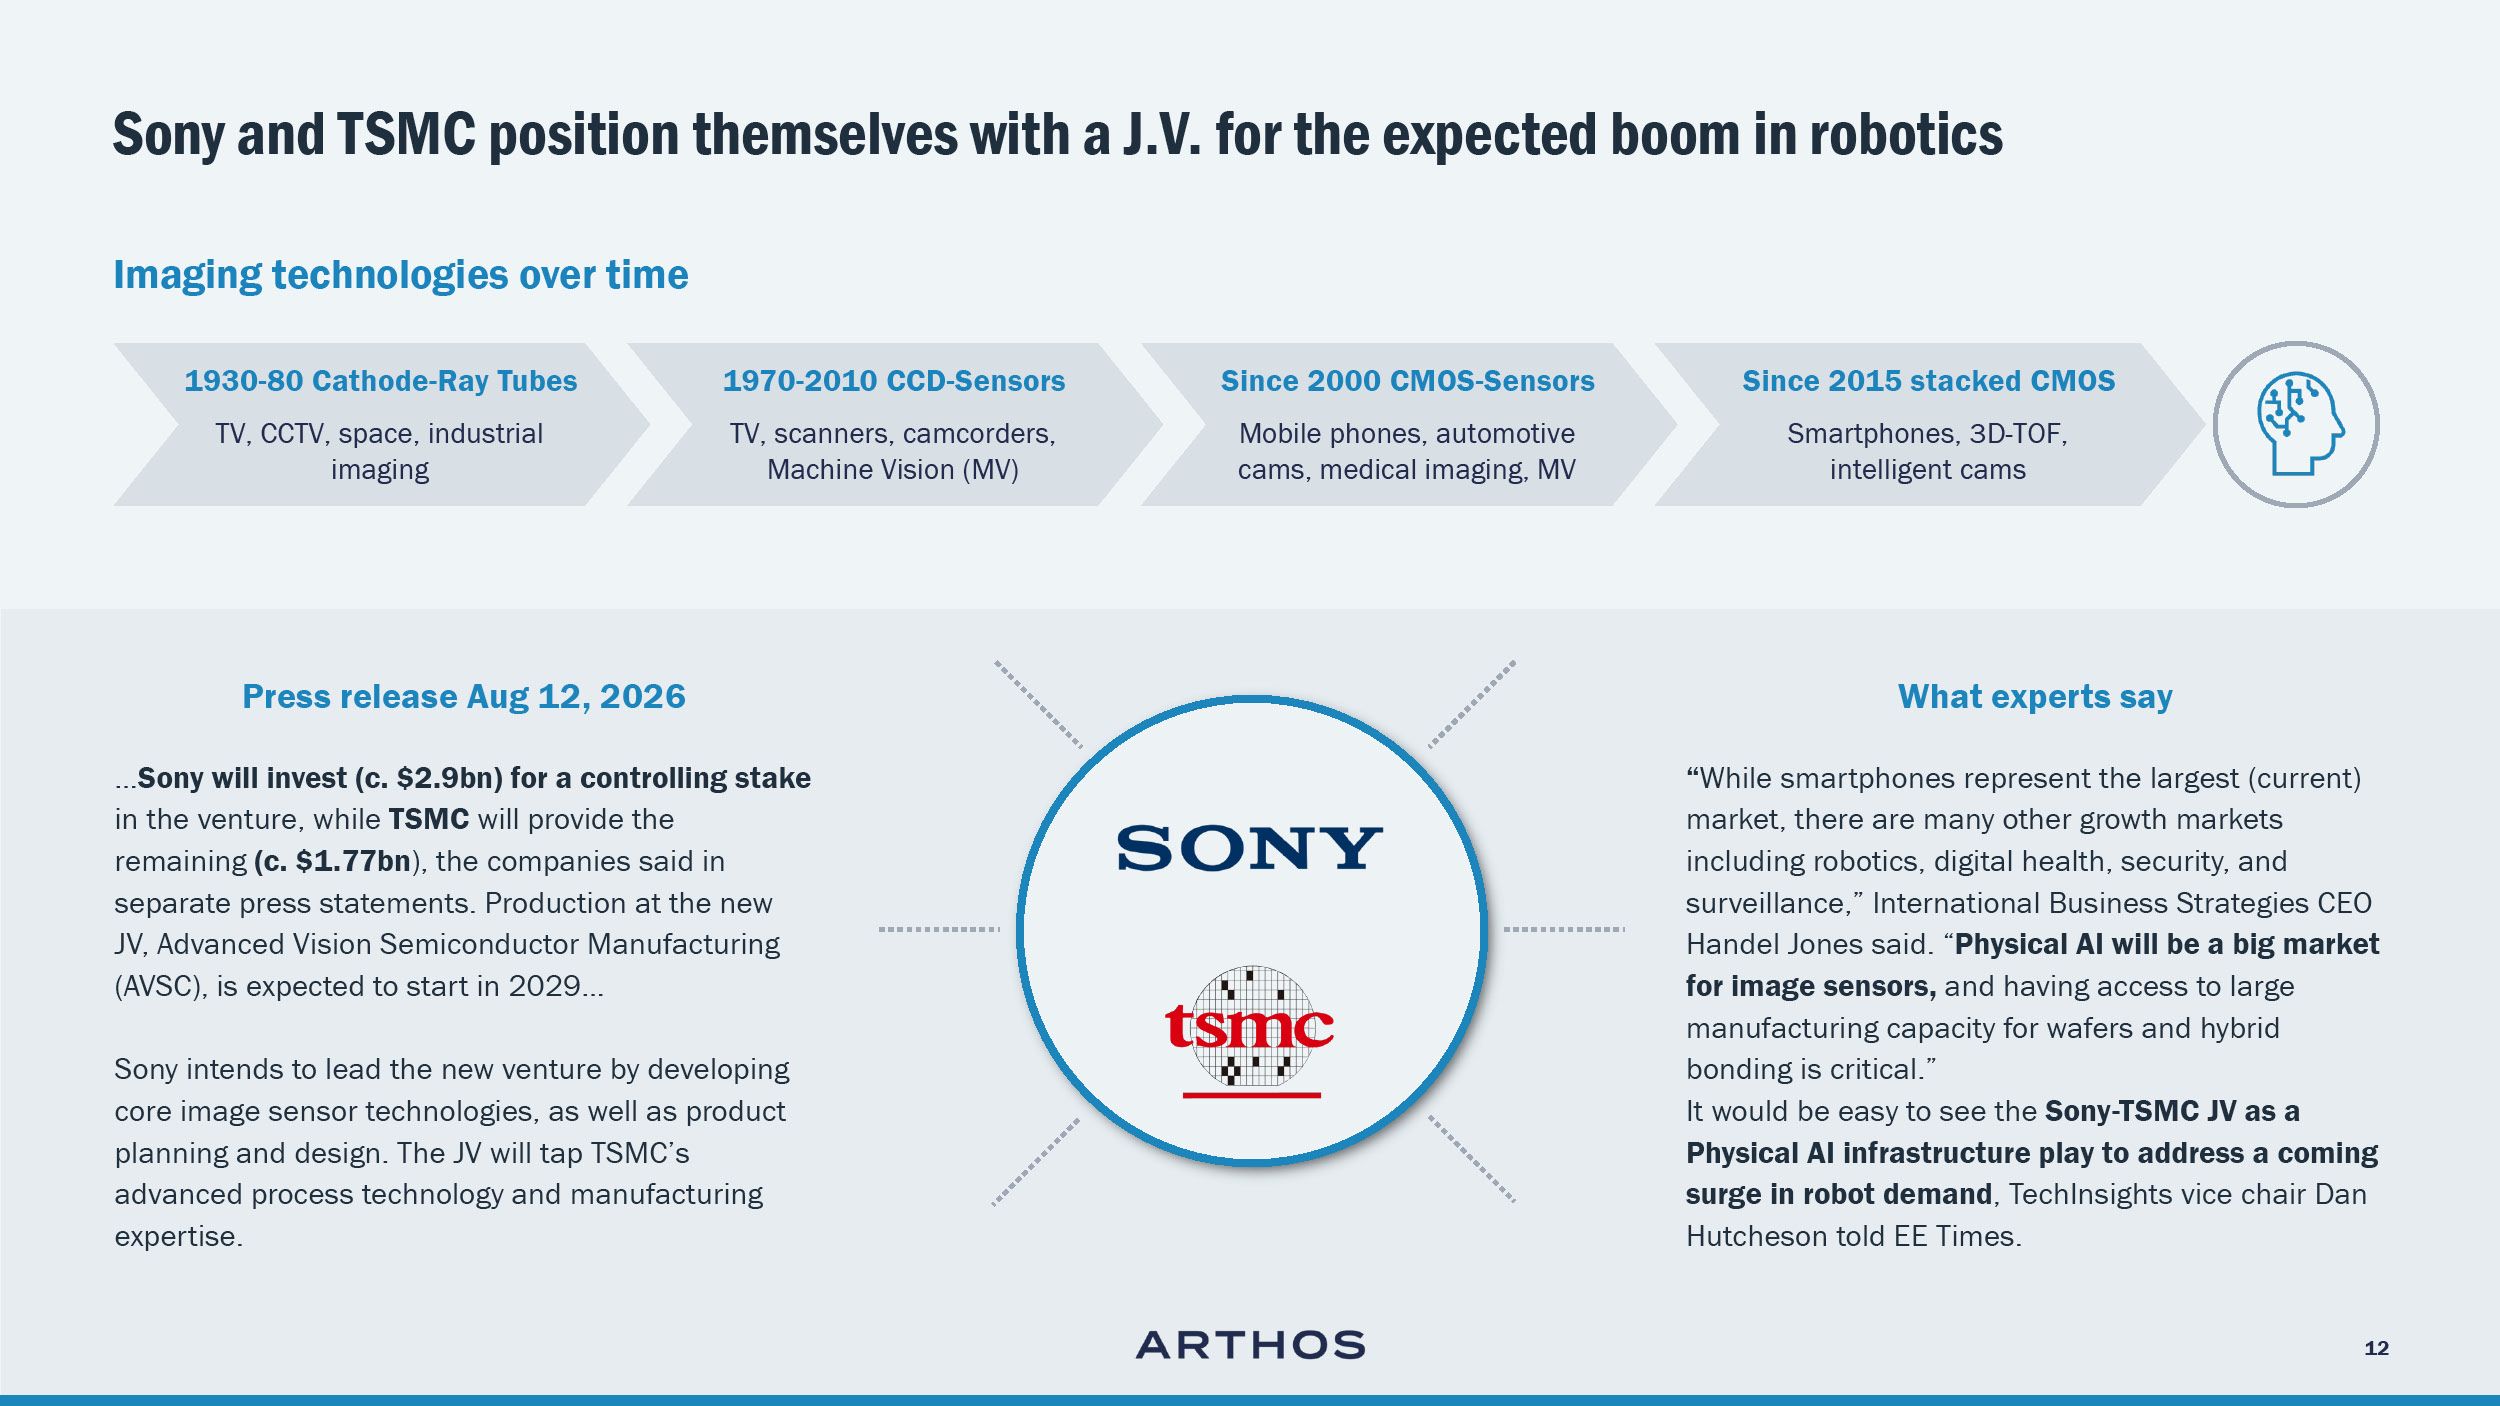
I am often asked whether the strong investments in AI infrastructure represent another hype cycle, such as the dot-com bubble in 2000 or the autonomous driving bubble in 2021. A major difference today is that valuations no longer rest only on NVIDIA and similar companies reflecting high growth expectations. The current market situation is characterised by full order books, ongoing infrastructure build-out, and delivery constraints. At the same time, the speed of the transition from Generative AI to Agentic AI and ultimately to Physical AI is more than impressive. You may have seen that Sony and TSMC decided to invest c. $5bn in a J.V. to address the expected surge in robot demand. We have moved beyond the stage where AI is primarily driven by expectations. Significant investments are now being translated into physical infrastructure and real capacity.
For more insights, valuation multiples, and notable transactions, sign up for our M&A Vision Newsletter to access the ARTHOS Vision M&A Report Q3 2026.
Sign up for our Vision newsletter to receive current and future reports:
We regularly publish analyses of M&A trends, valuation multiples, and transactions
Digital Services M&A Report Q3 2026
Digital Services M&A Report September 2026
Vision M&A Report Q2 2026
Semiconductor M&A Report Q2 2026
Software M&A Report Q2 2026
Software M&A Report March 2026
Computing & Connectivity M&A Report Q1 2026
Test & Measurement M&A Report Q3 2025
Software M&A Report Q3 2025
Digital Services M&A Report August 2025
Software M&A Report Q2 2025
Robotics M&A Report Q2 2025