

AI Boom Drives Stock Markets and Vision M&A Transactions
Vision M&A Report Q2 2026
September 2026 – M&A trends, valuation multiples and transactions
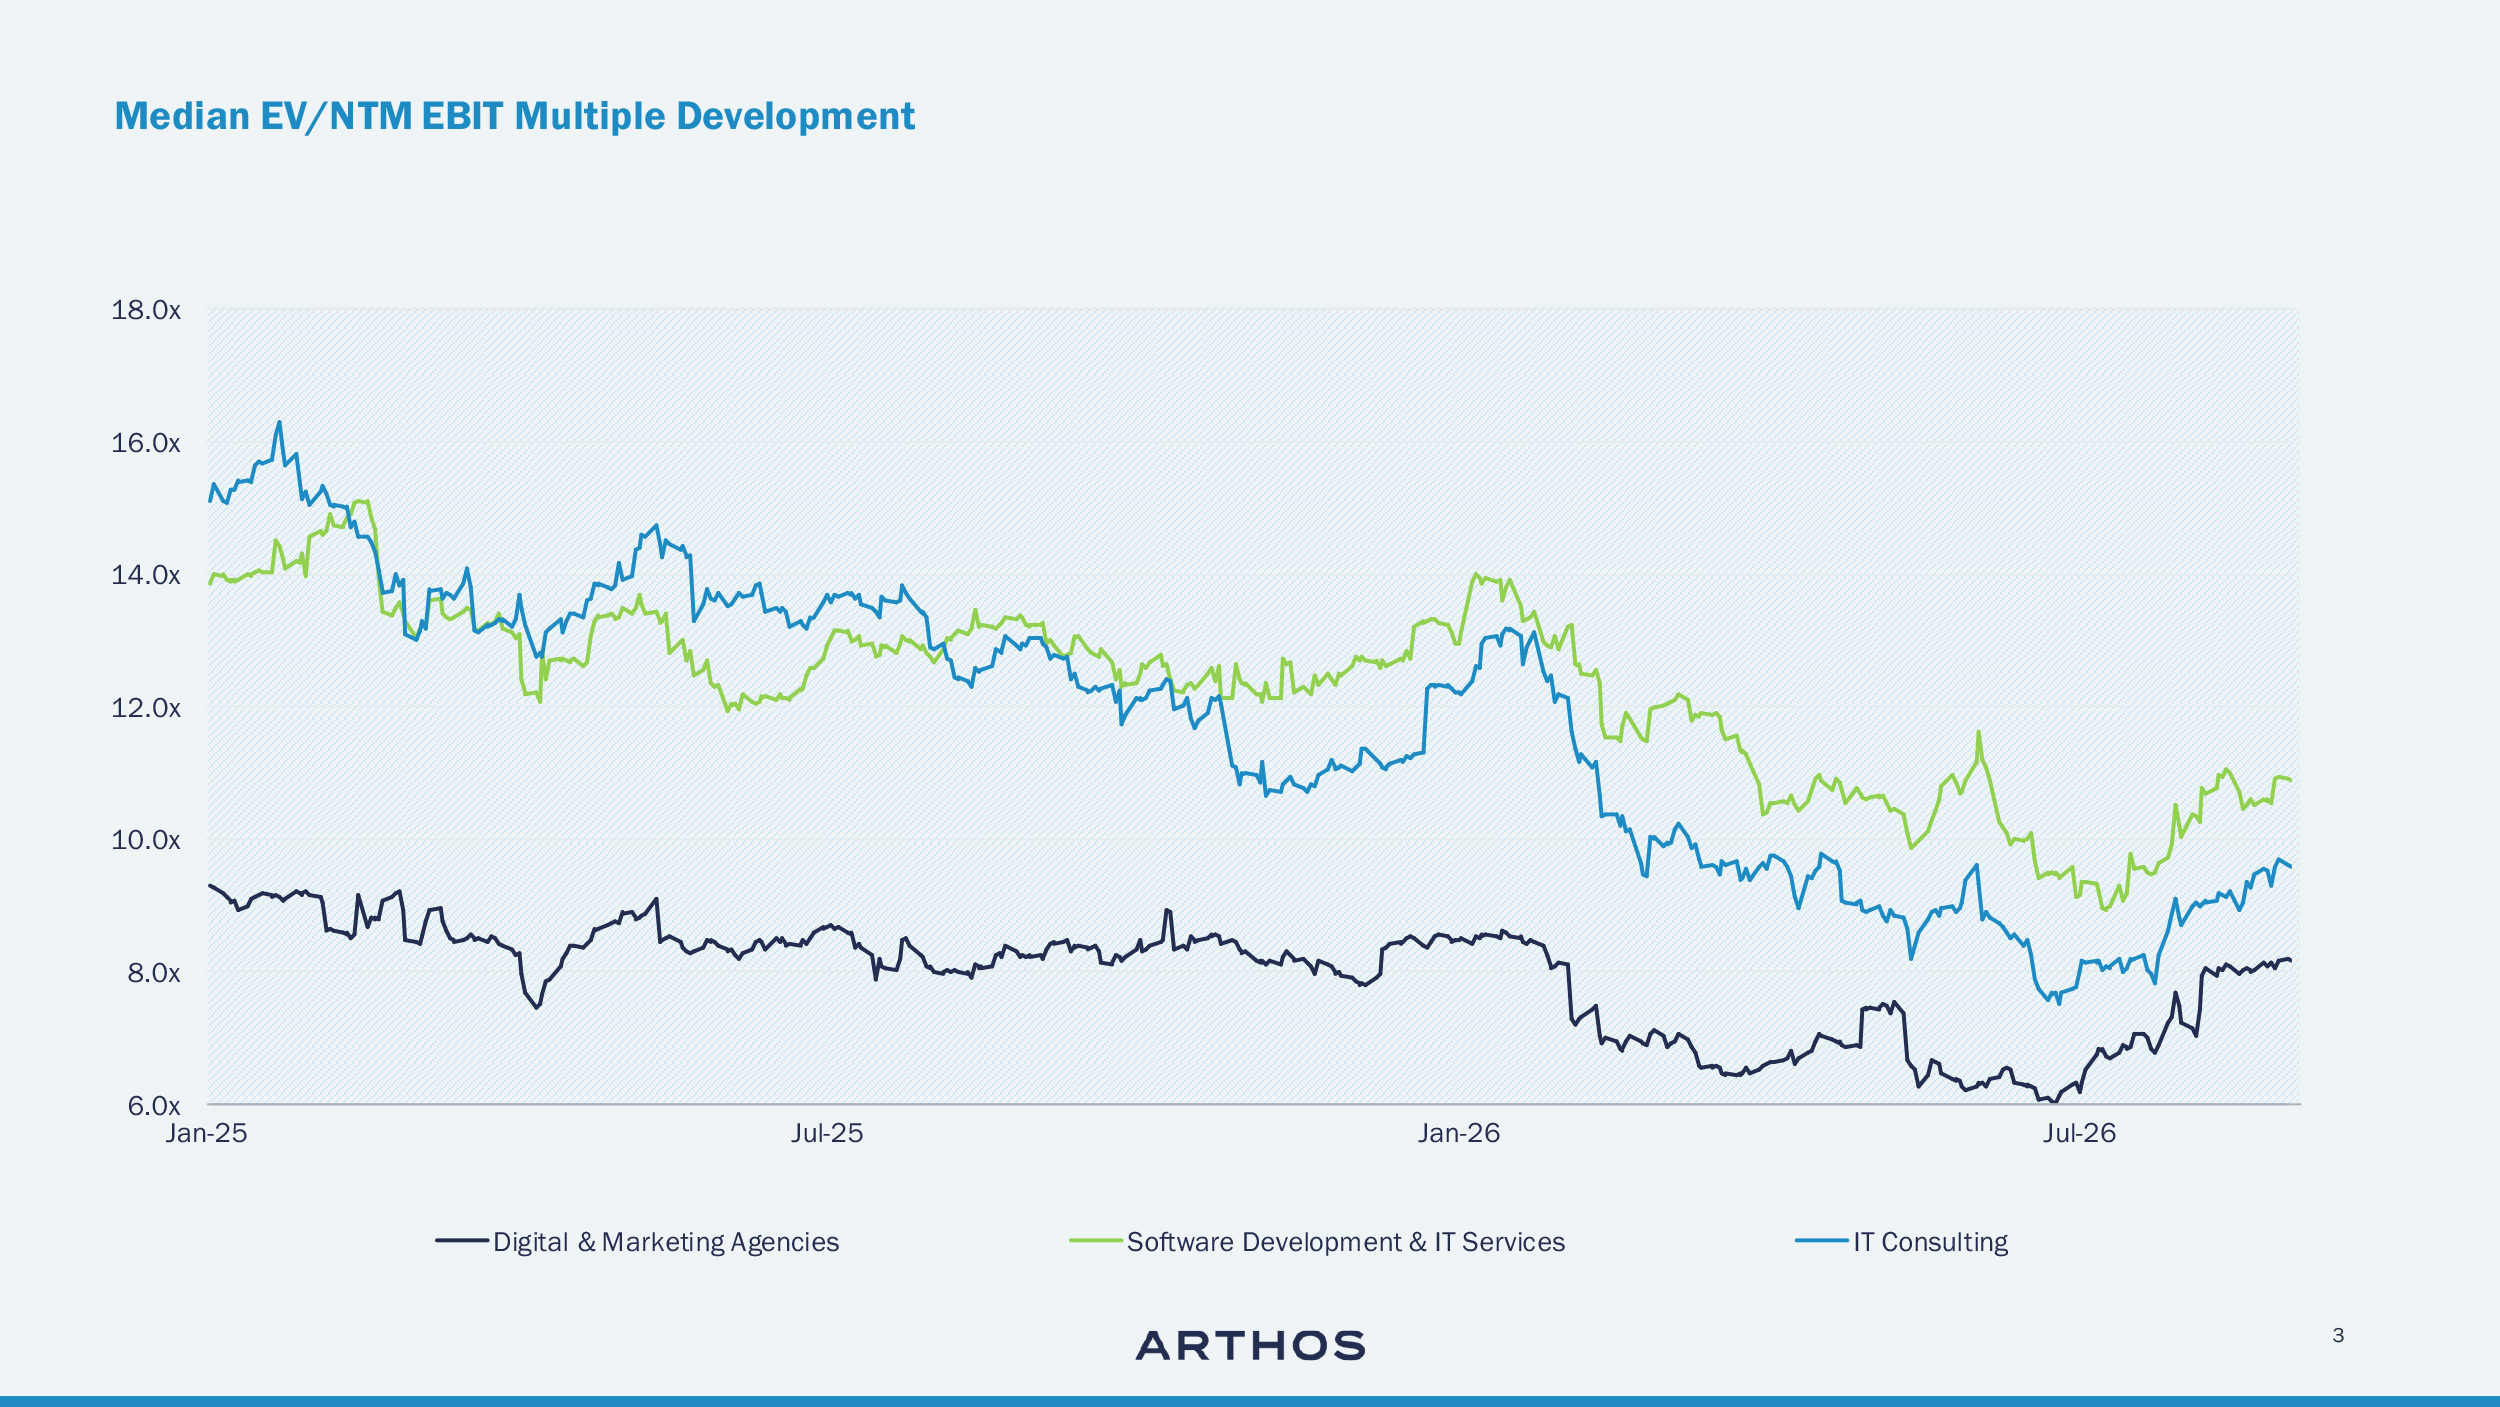
While the macroeconomic backdrop in Europe and Germany remains demanding, equity markets have looked through the noise. After a pronounced de-rating on AI disruption fears, culminating in the February 2026 sector sell-off, Digital & Marketing Agencies have rebounded by approximately 25% in recent months, as Publicis lifted its FY26 organic growth guidance.

Managing Partner ARTHOS
Expert in Digital Services & Software
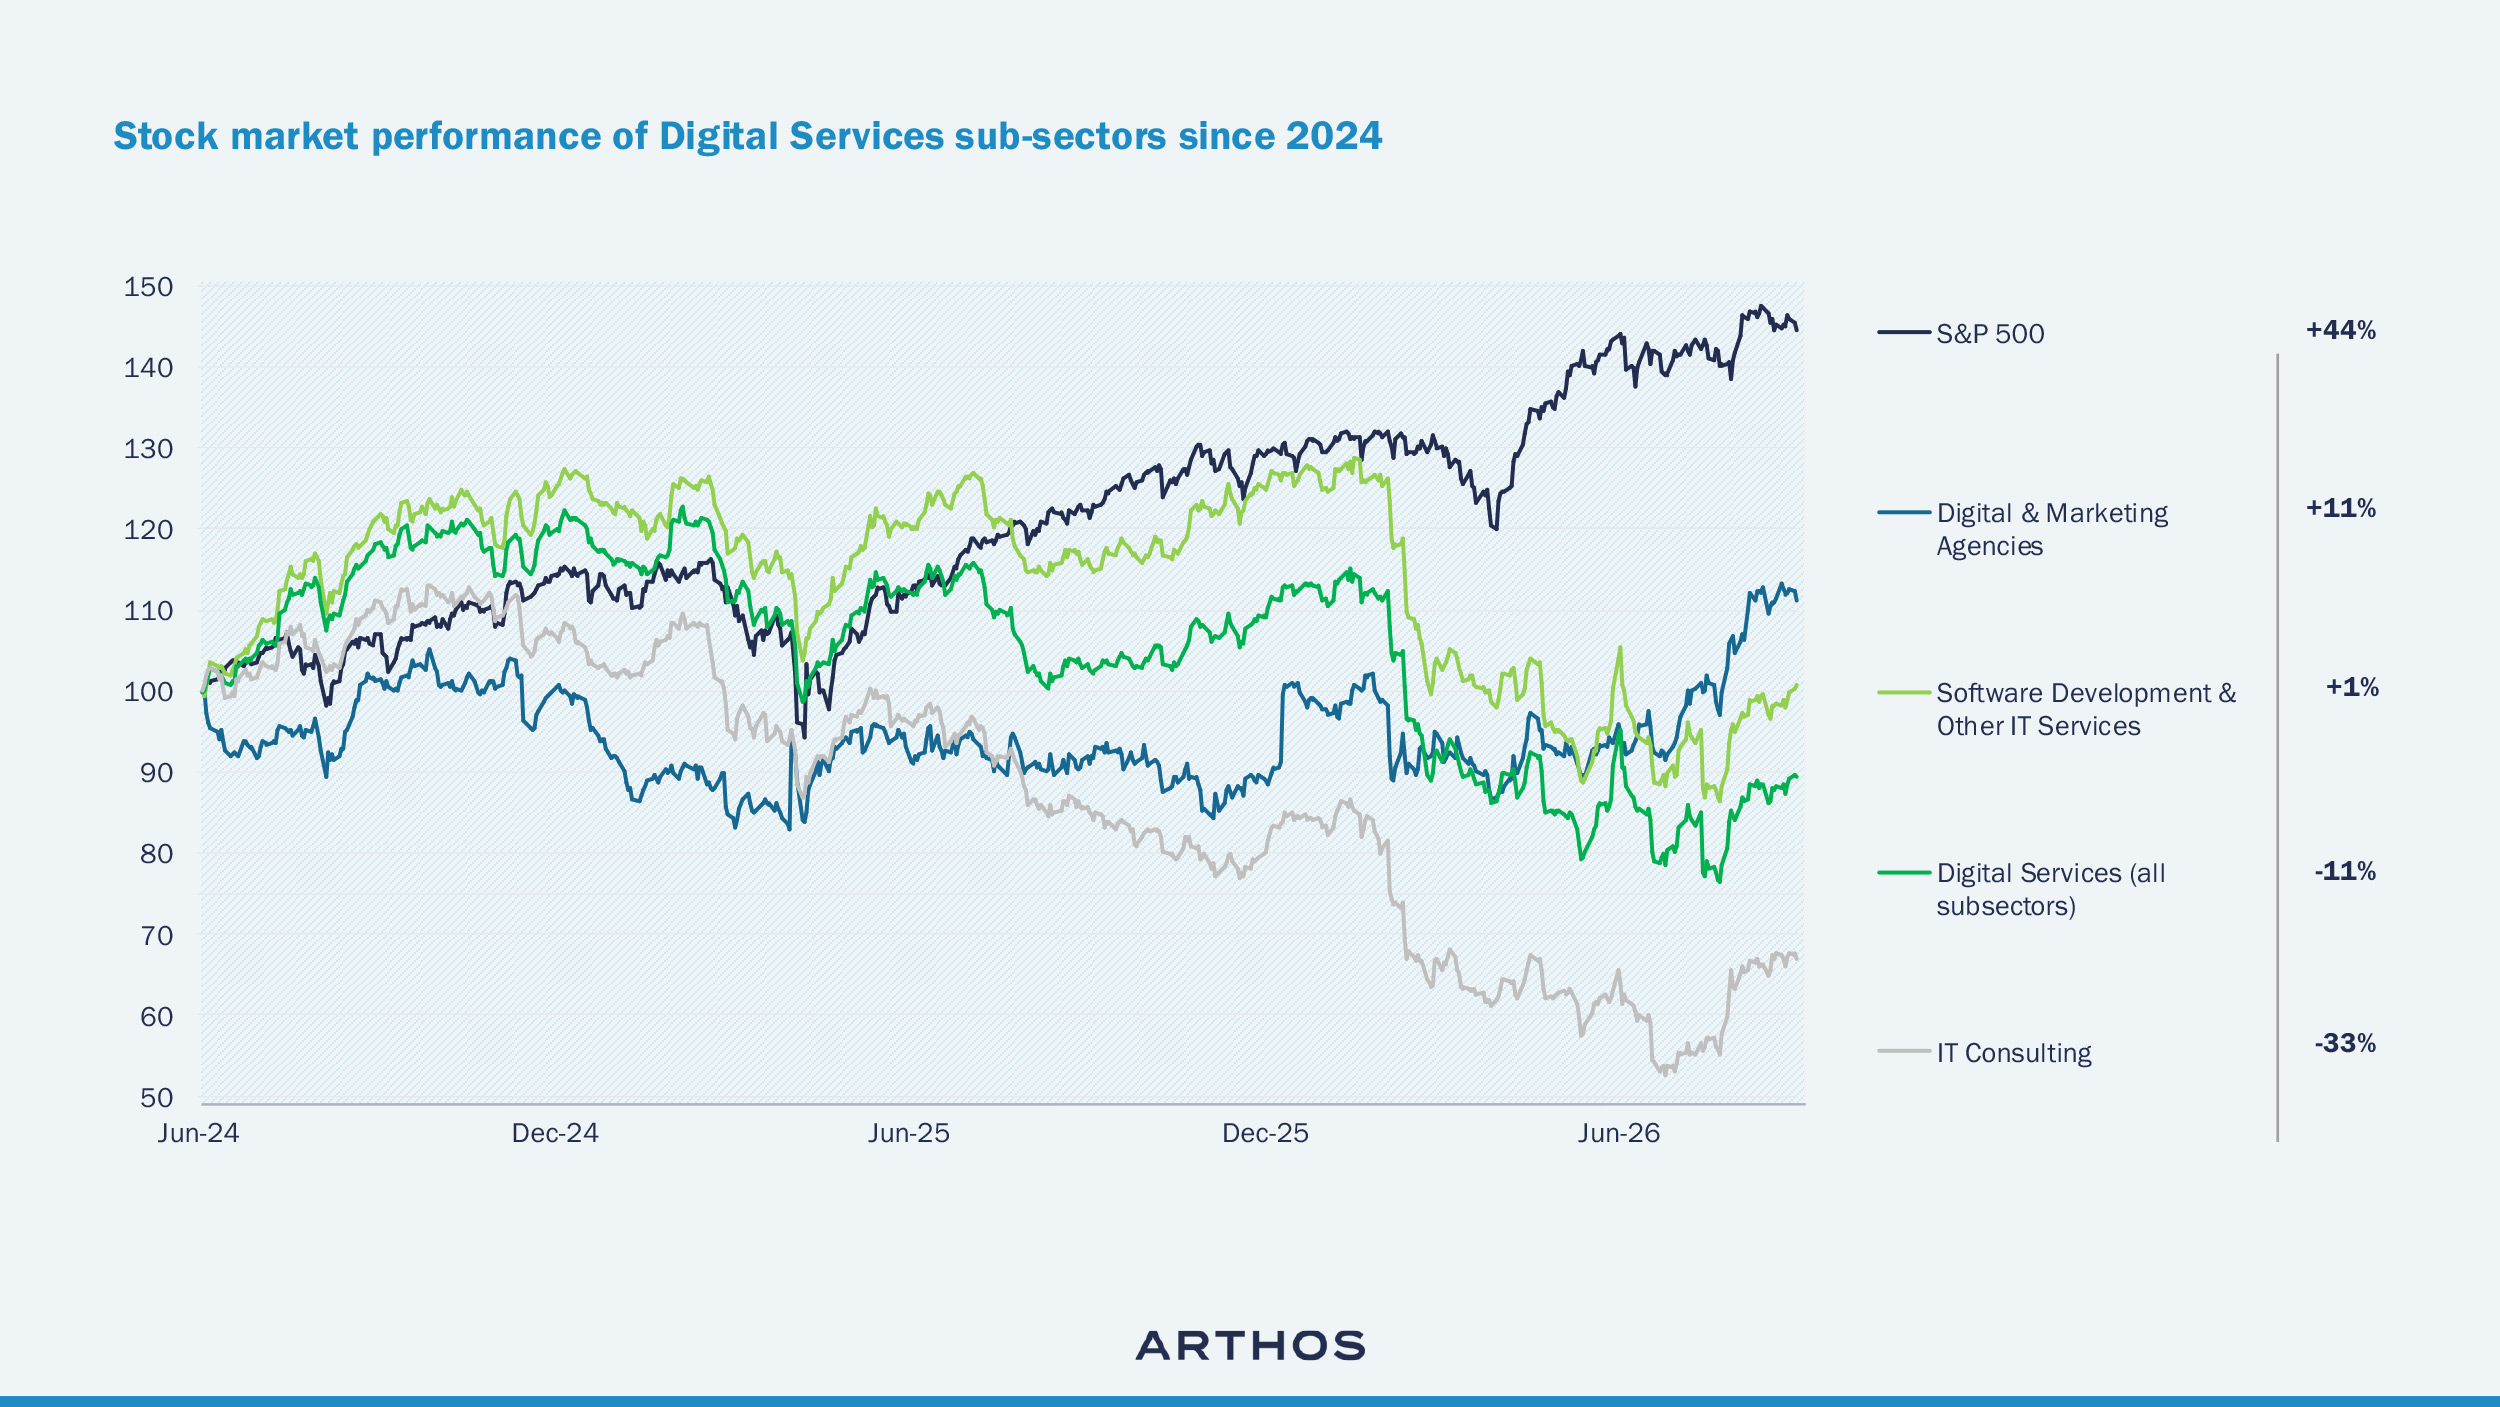
Valuations are recovering, but selectively. Sector trading multiples have re-rated from a low of ~6.0x in June to 8.2x NTM EV/EBIT in September 2026, though still well below early-2025 levels. In private markets, the spread is even wider: agencies with recurring retainers, proprietary data or productised AI tooling command 8–12x EBIT, while project-heavy, people-dependent models clear at 5–7x. The market is no longer pricing agencies – it is pricing business models.
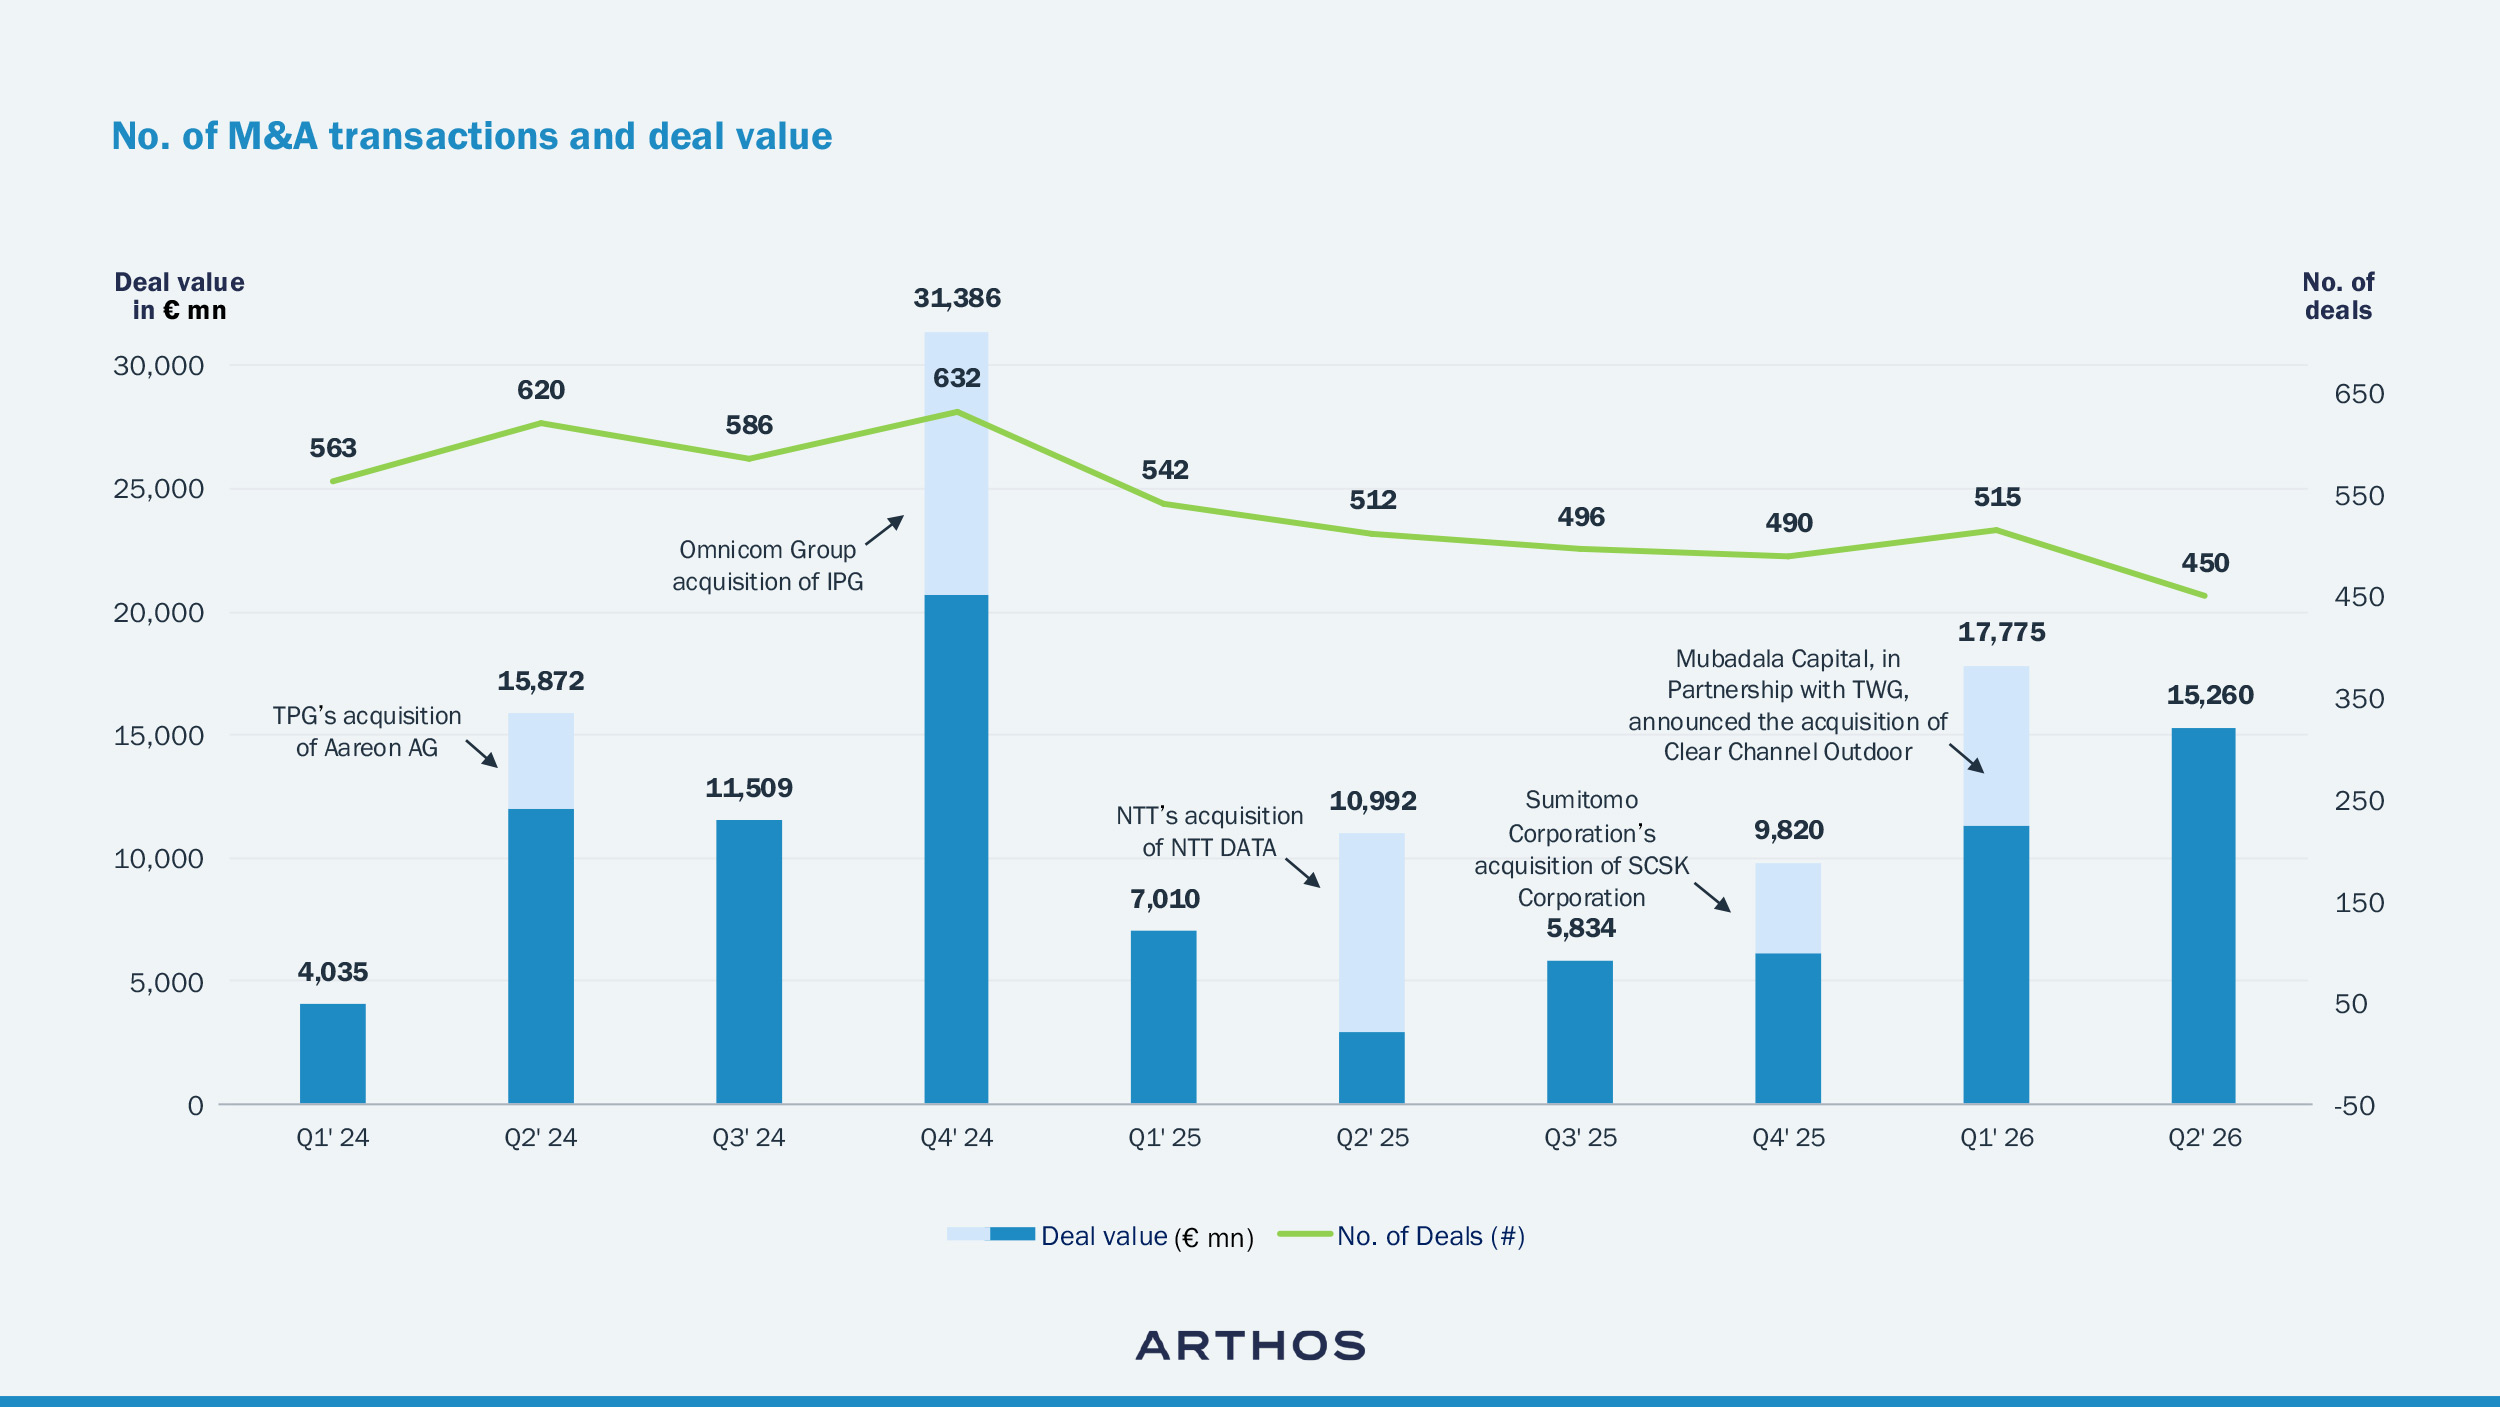
Deal activity has followed. Disclosed deal value more than doubled year-on-year to €12.2bn in H1 2026, albeit on fewer, larger deals.
Two forces drive this renewed positive M&A momentum: strategics are buying capability rather than capacity, and private equity executing buy-and-build around differentiated founder-led shops. Underlying both, generative AI is the hinge, compressing rate cards for commoditised services while raising the value of measurement, creator access and owned IP.
Looking ahead, prospective buyers will continue to concentrate on a handful of growth areas and will follow the channels that are winning the budget. Nearly 80% of global ad spend now flows into retail media, paid search and social platforms, with social media, connected TV and retail media each growing at low double-digit rates while linear TV is in structural decline.
The M&A market mirrors this shift: the most sought-after capabilities today are creator and influencer marketing, retail-media management and CTV expertise – evidenced by Accenture’s acquisition of Whalar, Publicis’ $2.2bn purchase of LiveRamp and more than 80 creator-economy acquisitions since early 2025. For German agencies with proven credentials in social commerce, creator activation
or retail-media execution, this translates directly into scarcity value with both strategic and financial buyers.
For German agency founders and owners, this is a rare alignment: recovering multiples, deep buyer pools and scarcity value for quality assets. We would welcome a confidential conversation on how these dynamics apply to your business.
For more insights, valuation multiples and notable transactions sign up for our M&A Digital Services Newsletter to access the ARTHOS Digital Services M&A Report September 2026.
Sign up for our Newsletter Digital Services to receive current and future reports:
We regularly publish analyses of M&A trends, valuation multiples, and transactions
Vision M&A Report Q2 2026
Semiconductor M&A Report Q2 2026
Software M&A Report Q2 2026
Software M&A Report March 2026
Computing & Connectivity M&A Report Q1 2026
Test & Measurement M&A Report Q3 2025
Software M&A Report Q3 2025
Digital Services M&A Report August 2025
Software M&A Report Q2 2025
Robotics M&A Report Q2 2025
Laser M&A Report Q2 2025
Vision M&A Report Q2 2025