

Vision – AI is not a Hype – it’s Real!
Vision M&A Report Q3 2026
Q3 2026 – M&A trends, valuation multiples and transactions
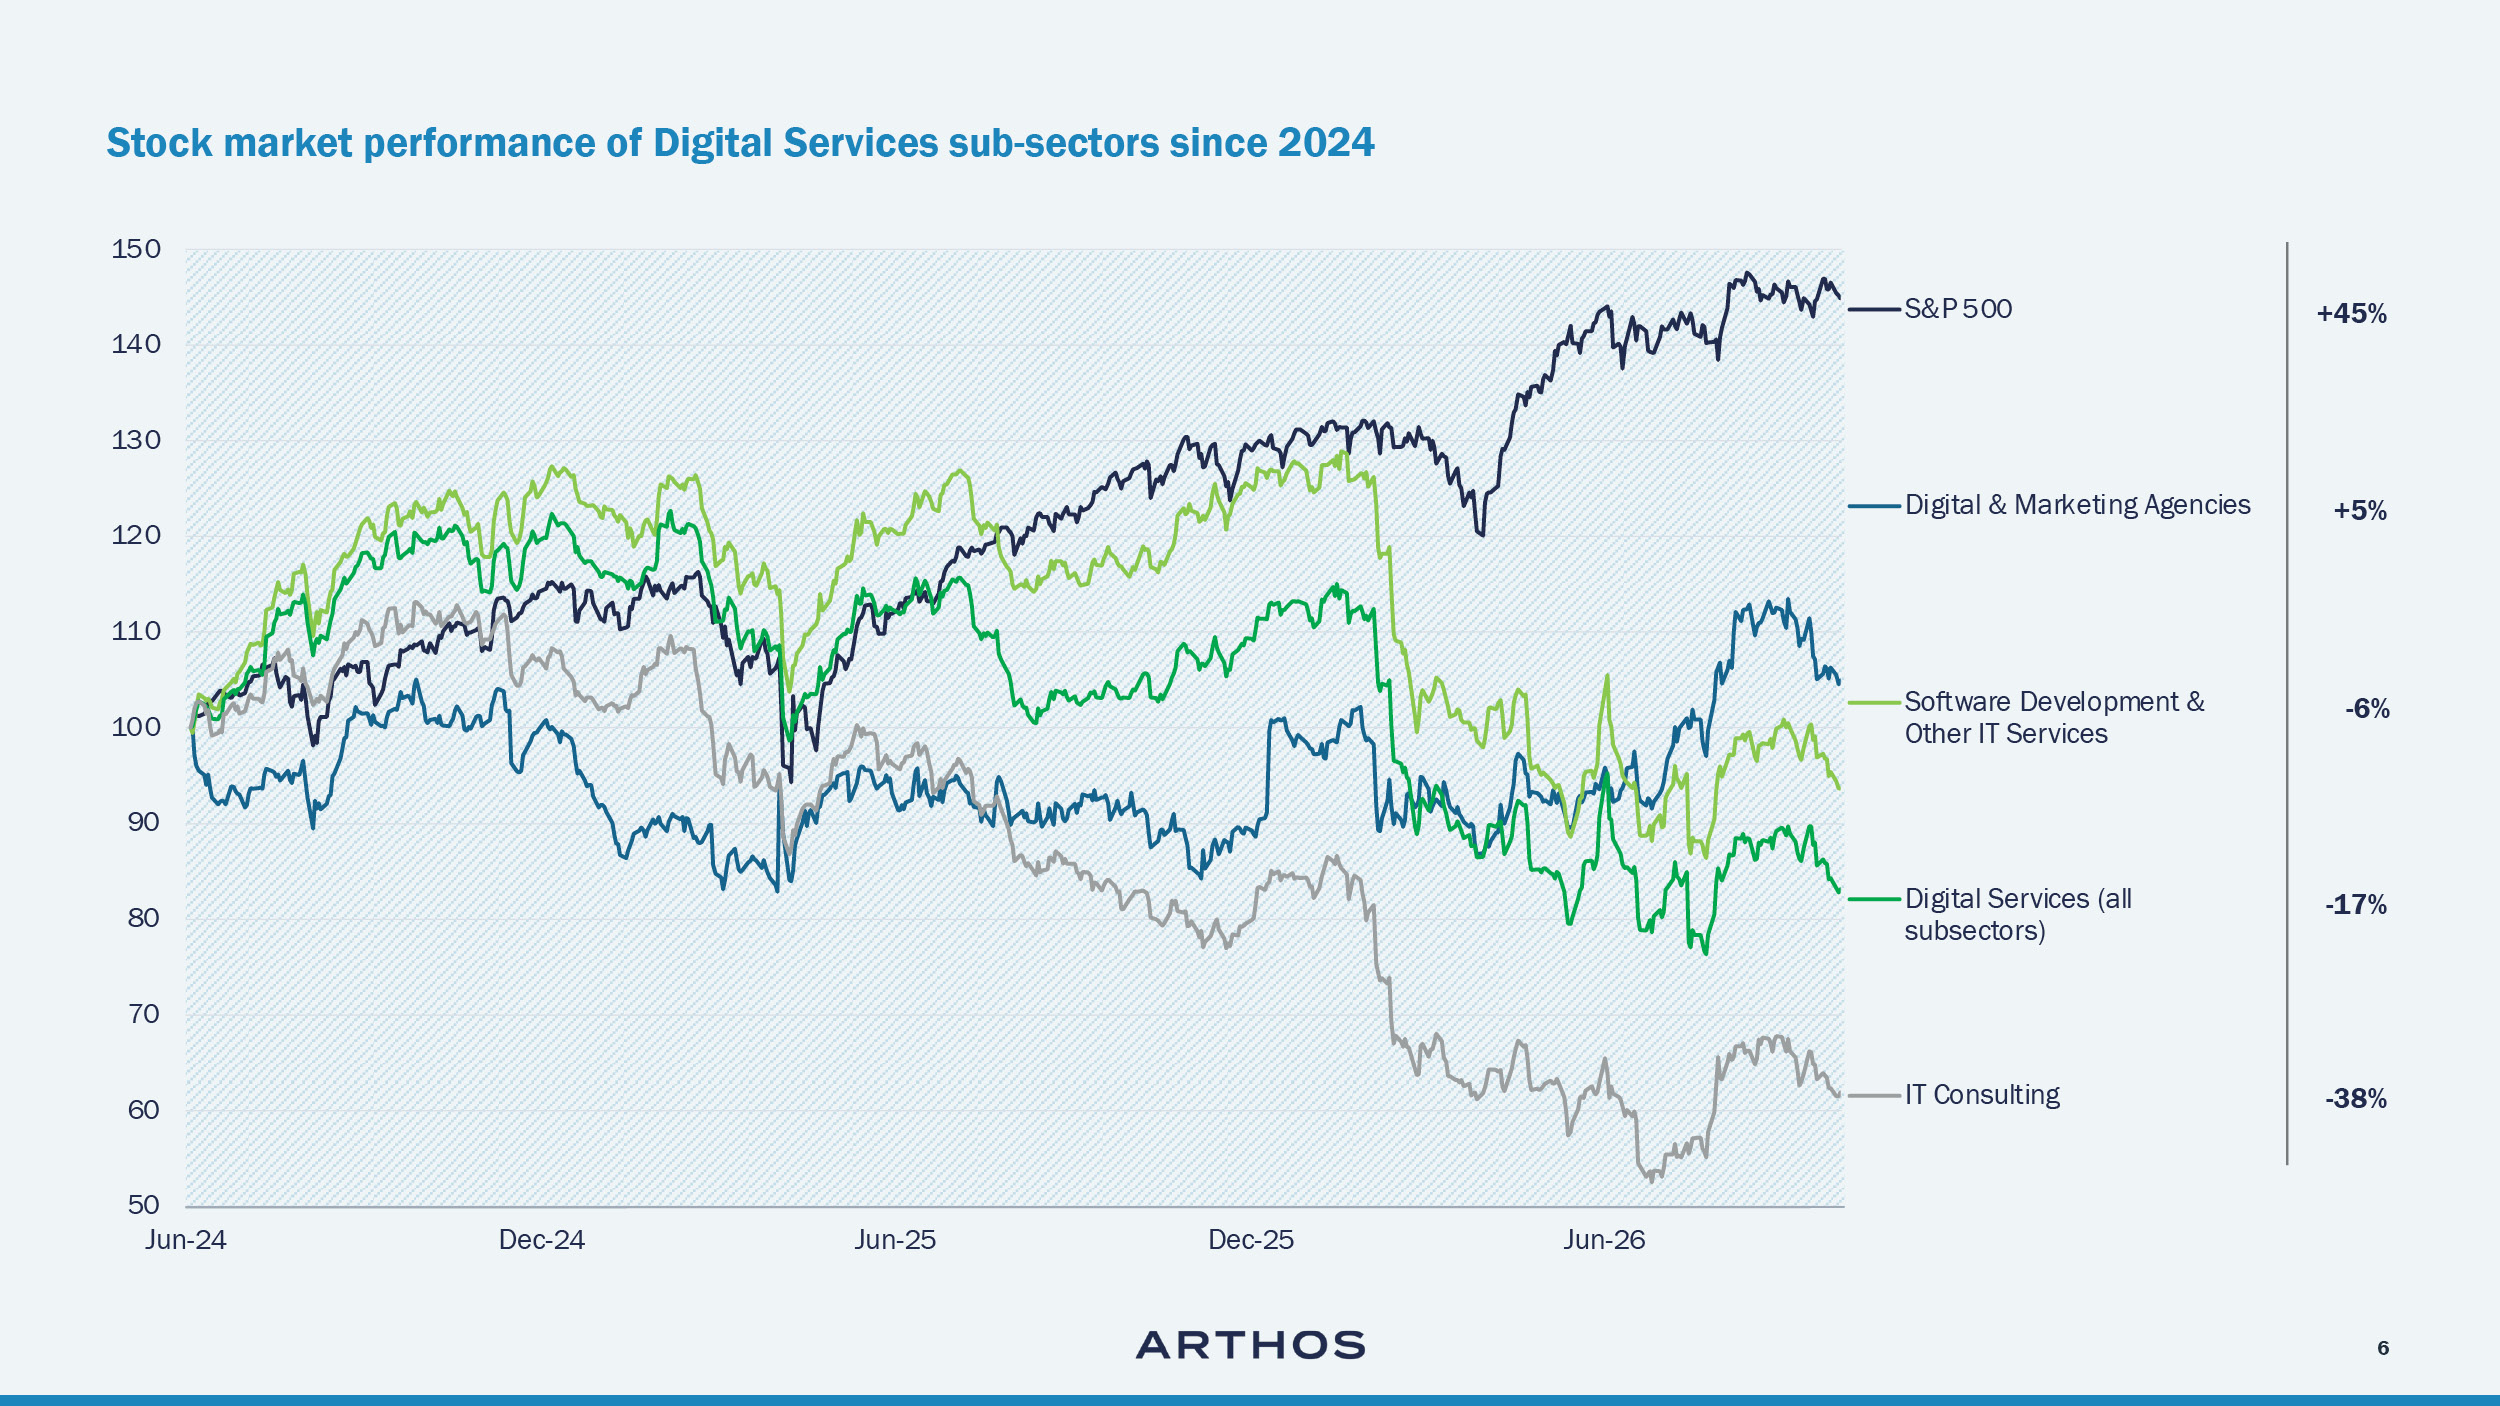
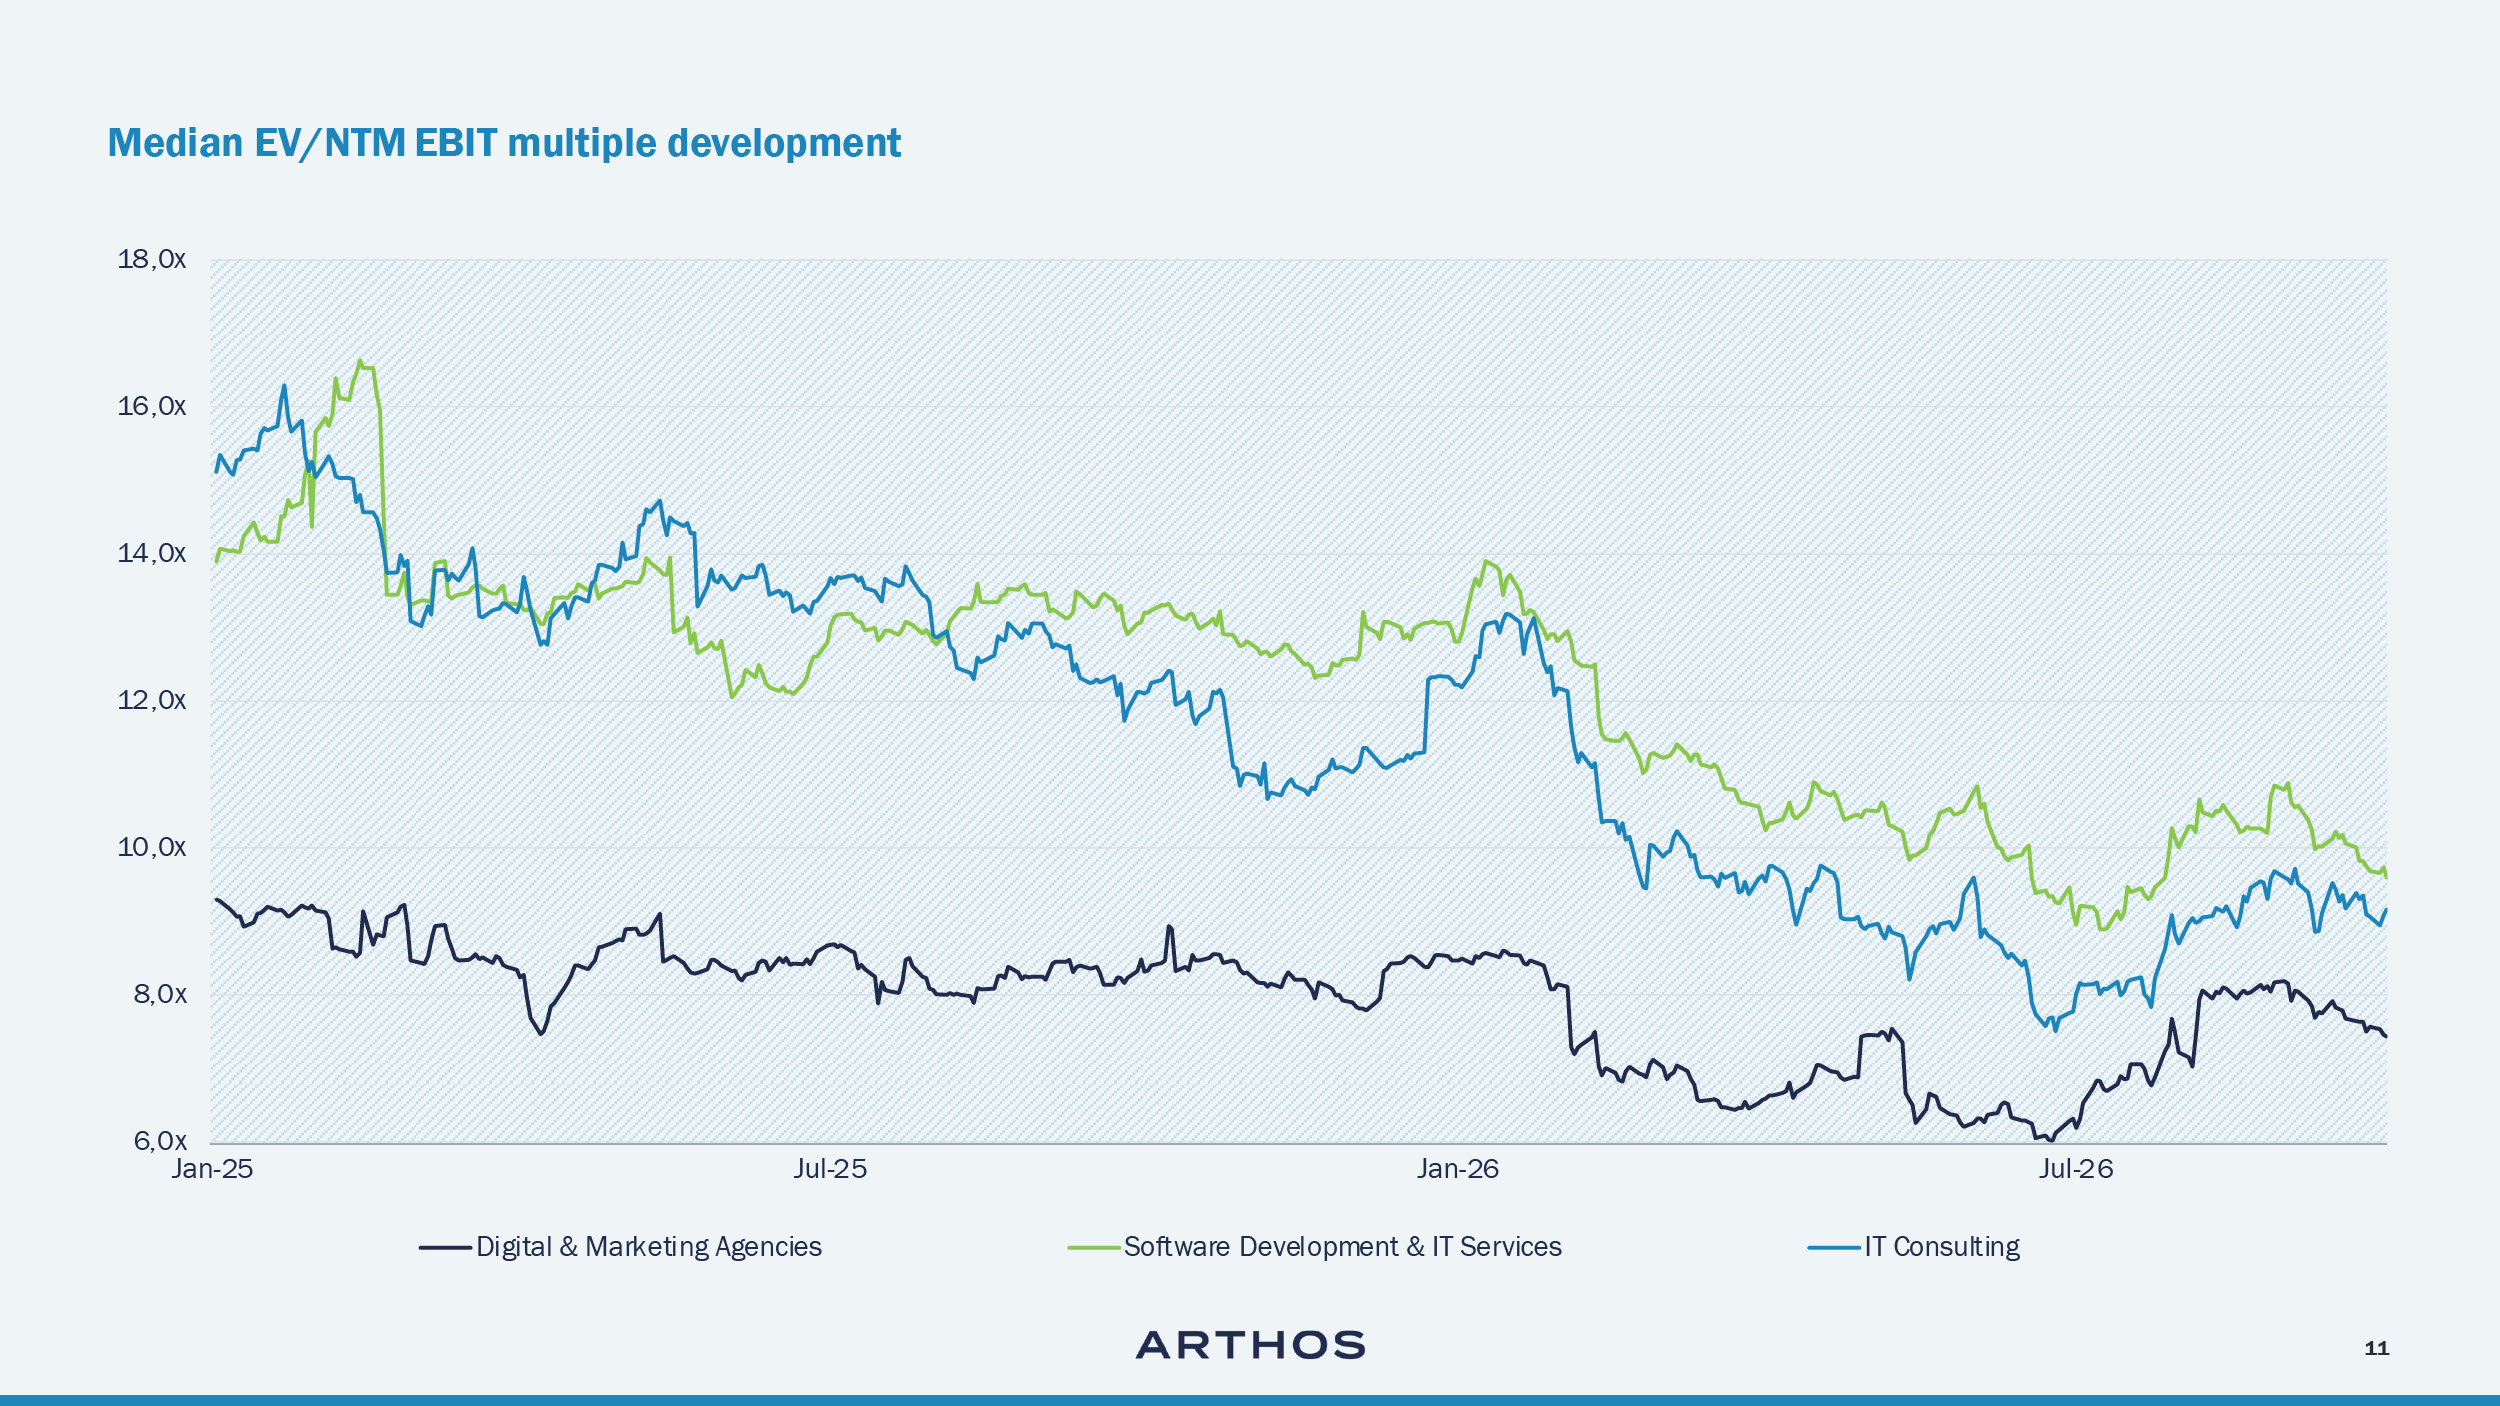
While the macroeconomic backdrop in Europe and Germany remains demanding, equity markets have looked through the noise. After a pronounced de-rating on AI disruption fears, culminating in the February 2026 sector sell-off, Software Development and IT-Services Companies have rebounded by approximately 10% in recent months with NTM EV/EBIT multiples recovering from ~9x in July to ~10x in September. On 1 October, Accenture reported quarterly revenue above its June guidance – a sign that AI is reshaping demand, not eroding it.
Managing Partner ARTHOS
Experte für Digital Services & Software
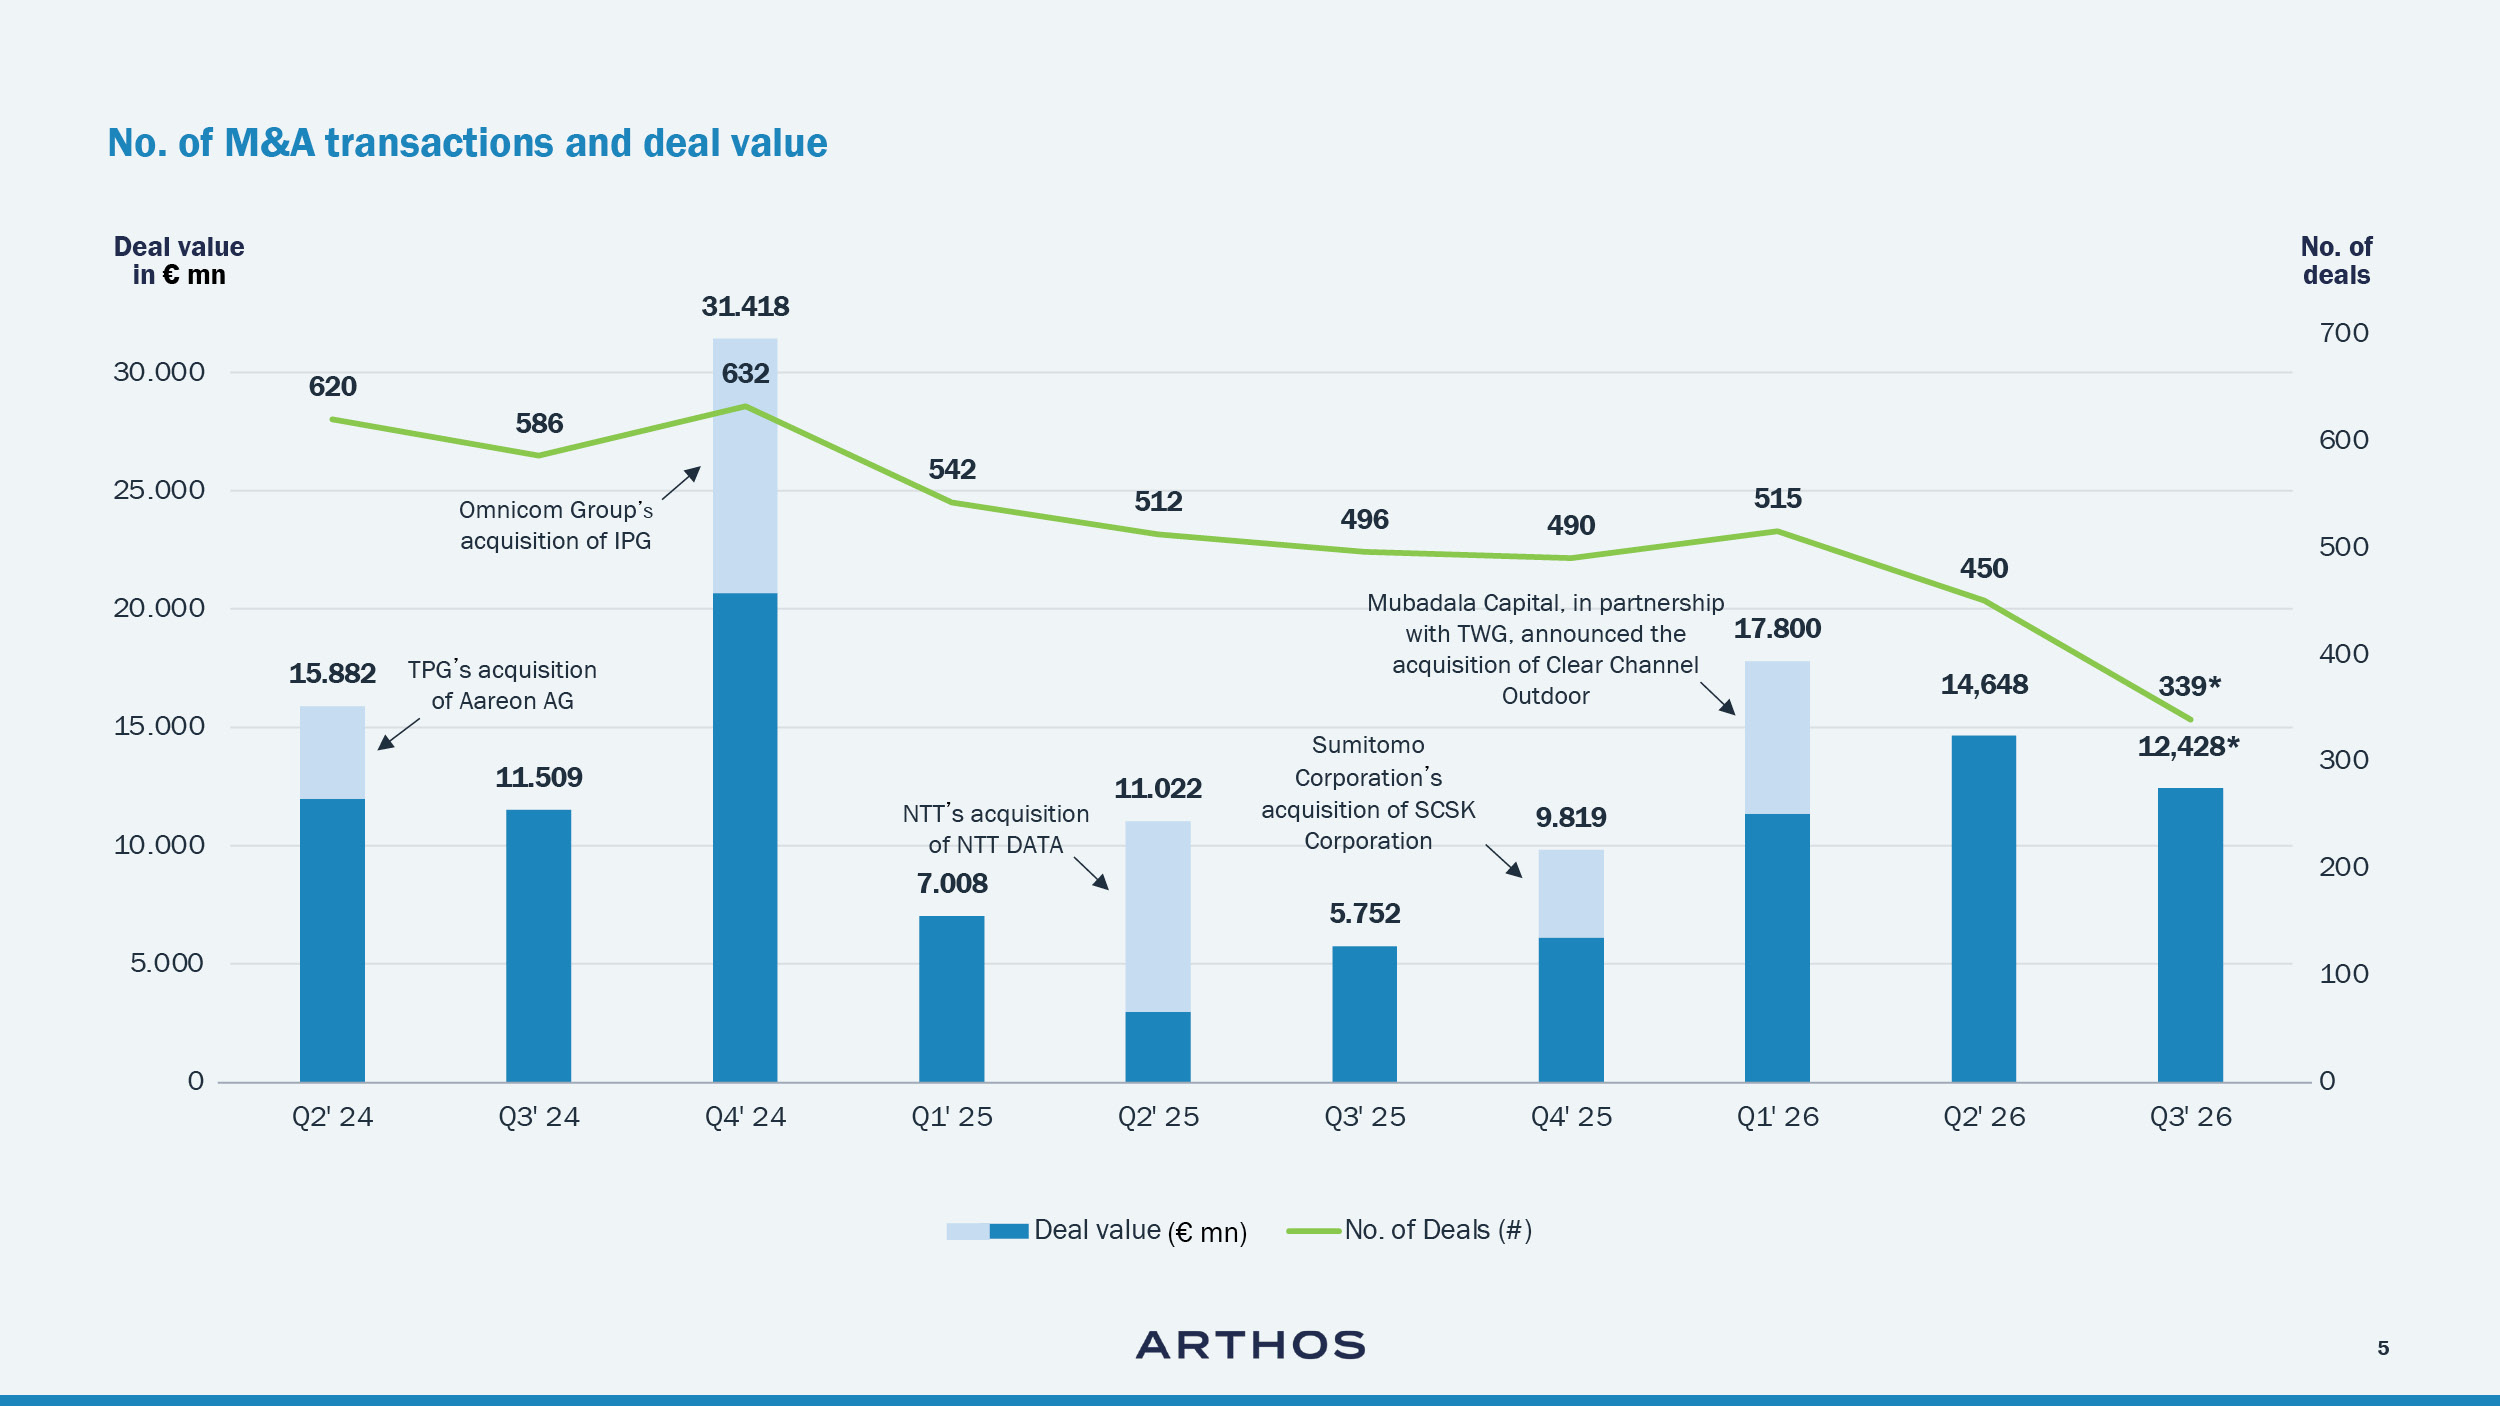
The M&A market never closed. Digital Services deal value rose 83% year-on-year to €33bn in H1 2026 – on fewer, but larger transactions – and strategic buyers continued to pay for capabilities: Accenture acquired Faculty (400+ AI engineers), VINCI Energies launched a bid for All for One, Persistent for Nagarro, Bridgepoint acquired iC Consult for €450m, Vodafone bought Skaylink for ~€180m and Synova chose Allgeier IT Services as a German buy-and-build platform. Many of these targets are Mittelstand-sized specialists.
What has changed is what buyers pay for. In the AI era, the market no longer prices IT service companies, it prices business models.
Areas that drive growth and command a premium today: recurring, contract-backed managed service revenue, deep platform and vertical expertise, legacy renovation, cybersecurity, and proven AI-enabled delivery that shows up in margins, not merely in fewer billable hours. Pure time-and-material capacity without differentiation faces margin pressure and a valuation discount.
For owners, two conclusions follow:
For more insights, valuation multiples, and notable transactions, sign up for our M&A Digital Services Newsletter to access the ARTHOS Digital Services M&A Report Q3 2026 with a focus on Software Development & IT Services.
Sign up for our Newsletter Digital Services to receive current and future reports:
We regularly publish analyses of M&A trends, valuation multiples, and transactions
Vision M&A Report Q3 2026
Digital Services M&A Report September 2026
Vision M&A Report Q2 2026
Semiconductor M&A Report Q2 2026
Software M&A Report Q2 2026
Software M&A Report March 2026
Computing & Connectivity M&A Report Q1 2026
Test & Measurement M&A Report Q3 2025
Software M&A Report Q3 2025
Digital Services M&A Report August 2025
Software M&A Report Q2 2025
Robotics M&A Report Q2 2025